Sydney Building Insurance
Contract Works Insurance in Sydney
Review construction insurance for your Sydney site.
Sydney Building Insurance
Review construction insurance for your Sydney site.
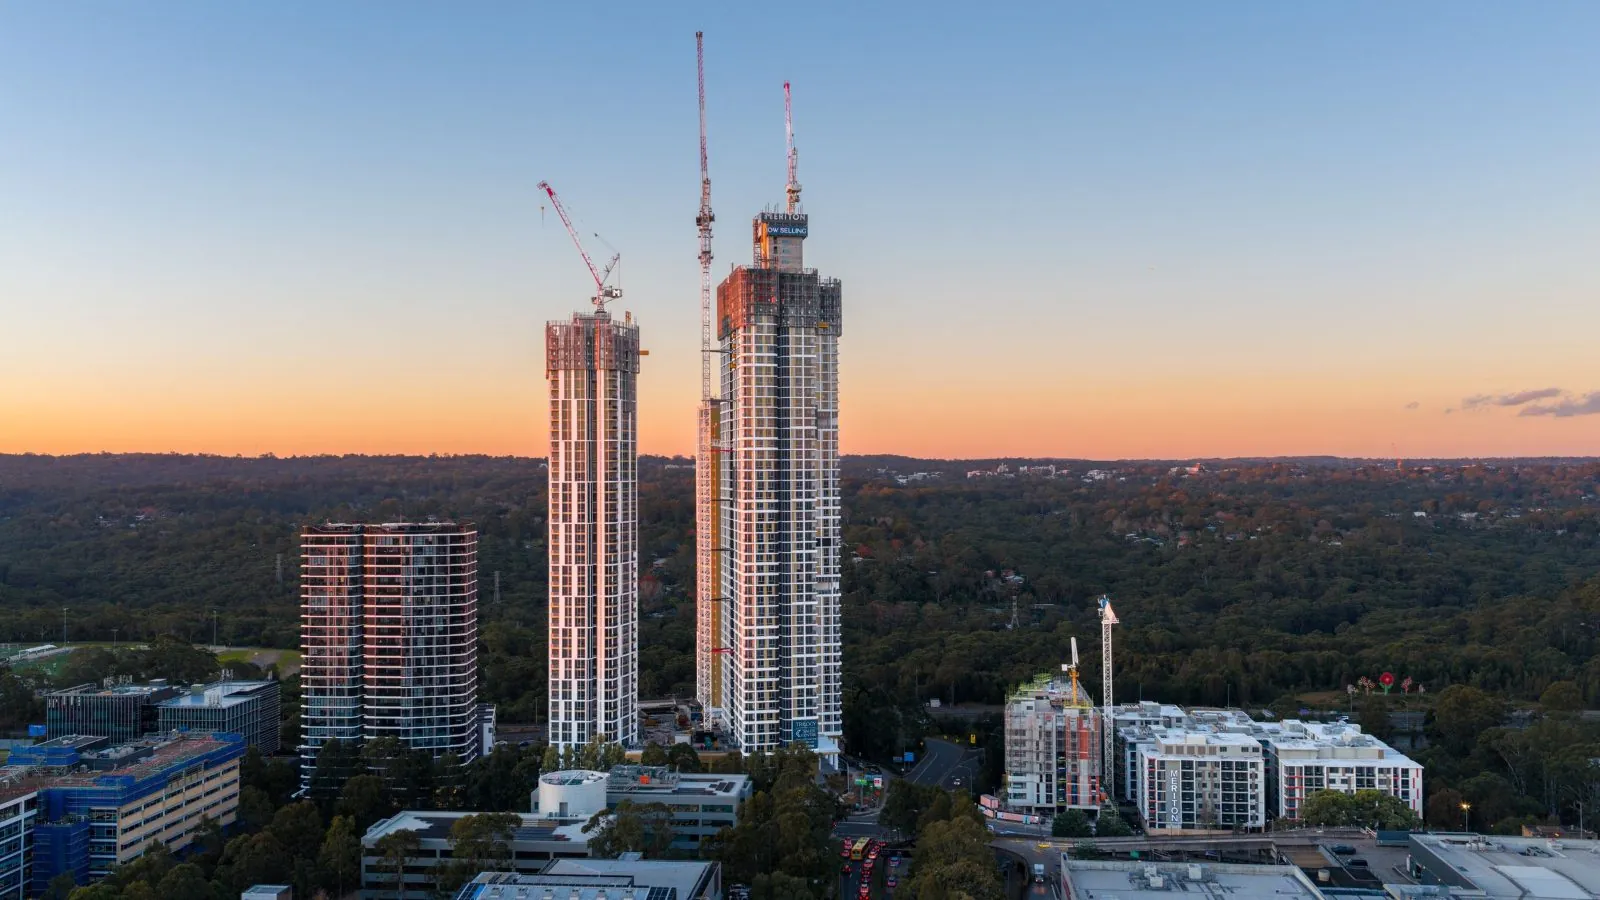
Contract works insurance in Sydney covers physical loss or damage to building work and materials on construction sites in Sydney, from events such as fire, storm, theft and accidental damage, until the project reaches practical completion.
Sydney projects range from high-rise and mixed-use towers to dual occupancy, knockdown-rebuild and renovation work in established suburbs, where work close to neighbouring buildings is a frequent underwriting question. Contract works insurance is separate from Home Building Compensation (HBC) insurance through icare HBCF, which New South Wales requires for most residential building work above a set value. PCIC Insurance arranges contract works cover for builders, developers and owner-builders working in Sydney from its South Melbourne office.
Sydney building projects often involve competing demands for space, access and construction time. Established eastern and inner suburbs contain older homes and closely positioned buildings, while Western Sydney continues to accommodate major residential growth. Commercial and mixed-use activity adds another layer of complexity. PCIC Insurance assists builders and project owners in Sydney who want to understand their options for insuring construction works.
Renovations in Paddington, Glebe and Marrickville can involve terraces, older masonry and narrow streets. Building on these sites may require careful coordination around neighbouring property, deliveries and temporary protection. On the North Shore, substantial home alterations can involve existing structures of significant value. The construction insurance enquiry should distinguish the declared works from the original building and identify relevant structural activities.
In areas such as Marsden Park, Oran Park and other Western Sydney growth locations, new residential building raises different considerations. Several contractors may operate across a development, with materials arriving in stages and construction schedules shifting. Insurers may ask about the project contract, construction value and insured parties. Builders undertaking repeated eligible projects can also investigate annual arrangements, provided their work fits within the policy conditions.
Sydney weather and site geography can affect work in progress. Coastal winds, heavy rain and storm events may expose unfinished roofs and materials, while some locations have flood-related risks. Steep or constrained sites can require specialised excavation and access arrangements. These factors should be described when relevant, especially if construction methods depart from ordinary residential work. For a project in Sydney, we can help identify the details that deserve attention.
PCIC Insurance services Sydney clients from South Melbourne. Jenny Hoang can help you discuss policy periods, project values, exclusions and available insurer terms. We encourage you to supply the actual construction details rather than relying on general descriptions. Whether the job is a townhouse development, major extension or commercial refurbishment, call 0468 034 450 to start a project-specific discussion.
Sydney builders and owner-builders deal with Building Commission NSW for licensing and permits. Strata and apartment work often comes with extra contract conditions, so send the insurance clause with your enquiry.
See also our New South Wales page.
Sydney projects are covered by New South Wales building law, including:
None of these statutory schemes replaces contract works insurance. Home warranty-type cover protects the homeowner when residential work is left incomplete or defective; contract works insurance covers physical loss or damage to the works while they are being built, and building contracts commonly state who must arrange it. The contract values that trigger statutory insurance change from time to time, so confirm the current threshold with the regulator before you sign.
We recognise the additional questions created by narrow access, adjoining buildings and structural alterations.
We welcome enquiries covering eligible renovations, new housing and commercial work.
We help explain important differences in the treatment of existing buildings and insured construction works.
Eligible knockdown rebuild projects may be considered, but demolition and the full work scope should be disclosed. Insurers may assess those activities separately or impose specific conditions. The timing of cover is also important.
Contract works cover generally focuses on the specified insured construction property. Damage to neighbouring property may involve separate legal liability considerations and policy conditions. Public liability and other relevant insurance should be reviewed where appropriate.
Some insurers may consider work in occupied buildings, subject to their underwriting rules. Occupancy, building use, structural work and the division between new and existing property are relevant. The proposed terms should be examined carefully.
Tell us about the project and Jenny Hoang will come back to you with questions or terms. Prefer to talk? Call 0468 034 450, Monday to Friday, 9:00am to 5:00pm.
Discuss your Sydney construction site with Jenny Hoang at PCIC Insurance. Call 0468 034 450.
No obligation to proceed. Monday to Friday, 9:00am to 5:00pm.
We also take enquiries from Parramatta, Penrith, Liverpool, Campbelltown, the Northern Beaches, the Central Coast and the Blue Mountains.