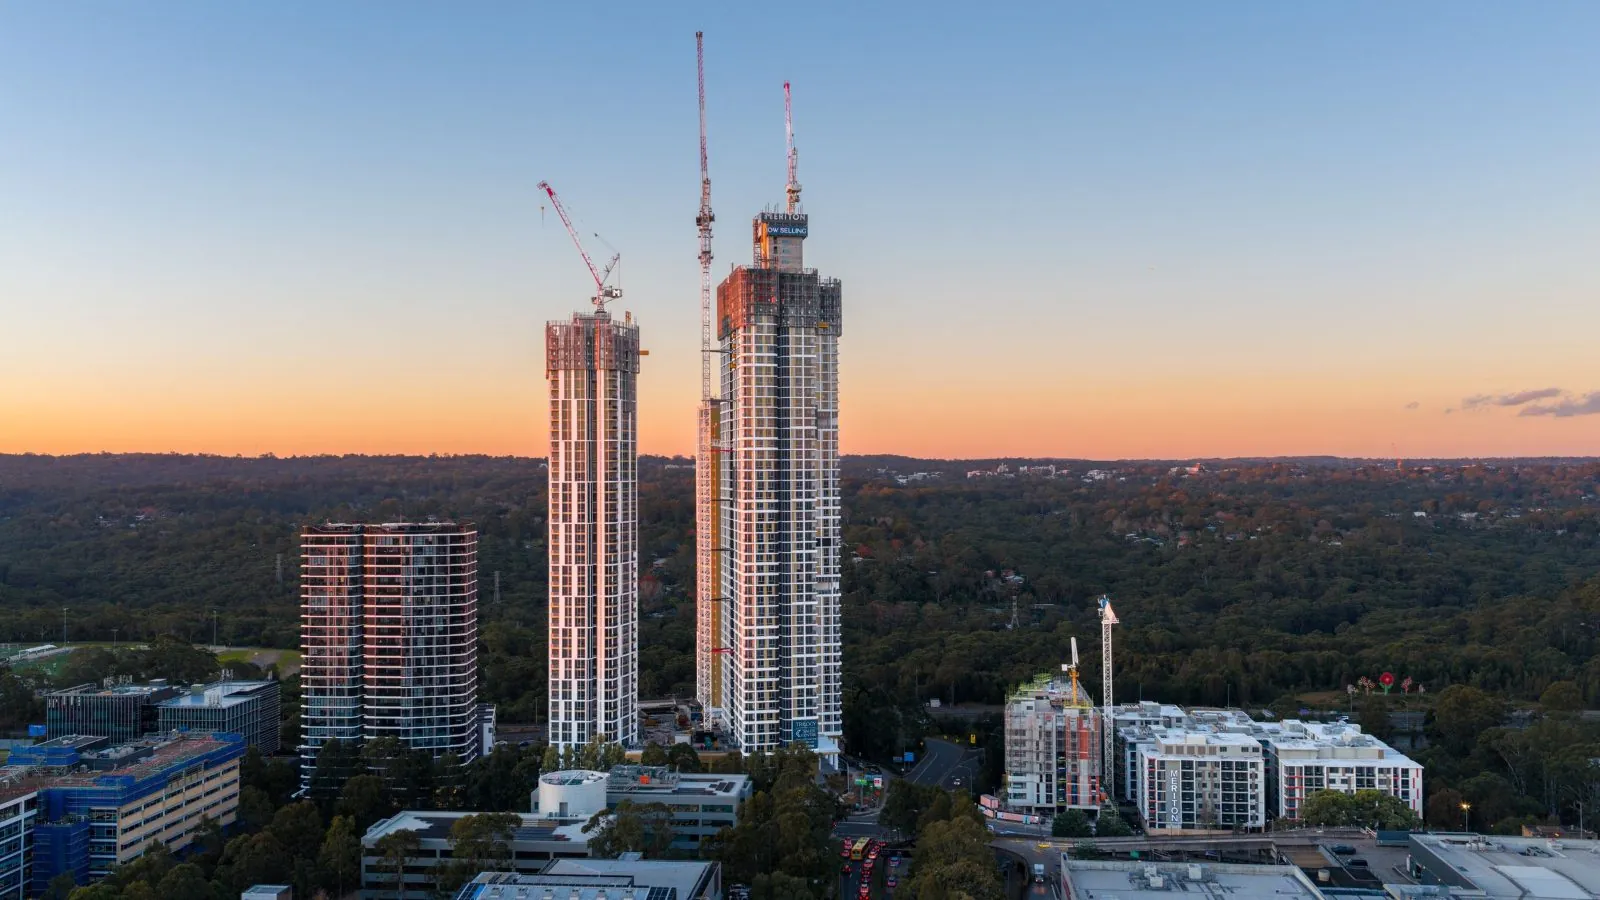
Sunshine Coast Building Insurance
Contract Works Insurance in Sunshine Coast, QLD
Review insurance for your Sunshine Coast project.
Sunshine Coast Building Insurance
Review insurance for your Sunshine Coast project.
Contract works insurance on the Sunshine Coast covers physical loss or damage to building work and materials on construction sites on the Sunshine Coast, from events such as fire, storm, theft and accidental damage, until the project reaches practical completion.
Sunshine Coast projects include new estates around Caloundra, beachside builds at Maroochydore and Noosa, and hinterland homes on sloping blocks. Contract works insurance is separate from the Queensland Home Warranty Scheme, which Queensland requires for most residential building work above a set value. PCIC Insurance arranges contract works cover for builders, developers and owner-builders working on the Sunshine Coast from its South Melbourne office.
The Sunshine Coast has a broad mix of construction activity, from coastal home renovations to new residential development and building work in the hinterland. Noosa, Maroochydore and Caloundra each have established neighbourhoods and changing commercial areas, while communities around Palmwoods and Maleny have different terrain and site conditions. PCIC Insurance helps construction clients discuss cover that reflects these local differences.
Renovating a home near the coast may involve work on an occupied property, access restrictions and exposure to weather before the building is fully enclosed. In established areas around Mooloolaba and Buderim, projects can include substantial extensions and changes to existing structures. The policy treatment of new work and the original building deserves attention, particularly where structural alterations are significant.
Moving inland, hinterland construction may involve sloping blocks, limited site access and surrounding vegetation. Heavy rainfall can complicate earthworks, drainage and temporary protection. These practical factors should be managed on site and accurately disclosed where relevant to the insurance assessment. The availability of insurance for a particular natural hazard depends on the proposed policy terms and any insurer conditions.
The Sunshine Coast also has new residential development, including projects around Aura near Caloundra and other growing communities. Builders undertaking repeated eligible homes may wish to consider annual contract works arrangements, while an individual project owner can explore a policy for the nominated job. Both approaches require clear information about the building activities and period of construction. If the site is on the Sunshine Coast, we can discuss the key questions before seeking terms.
PCIC Insurance services the Sunshine Coast from South Melbourne. Jenny Hoang can assist with enquiries about project-specific insurance, existing property and weather-related policy terms. We encourage clients to identify the exact location and building method rather than assuming a coastal project and a hinterland project present identical risks. Contact us on 0468 034 450 with a description of your work.
On the Sunshine Coast, licensing and owner-builder permits come through the Queensland Building and Construction Commission (QBCC). Coastal and hinterland sites can be assessed differently, so give the insurer the exact address.
See also our Queensland page.
Sunshine Coast projects are covered by Queensland building law, including:
None of these statutory schemes replaces contract works insurance. Home warranty-type cover protects the homeowner when residential work is left incomplete or defective; contract works insurance covers physical loss or damage to the works while they are being built, and building contracts commonly state who must arrange it. The contract values that trigger statutory insurance change from time to time, so confirm the current threshold with the regulator before you sign.
We recognise differences in terrain, weather and site access across the Sunshine Coast.
We help clients examine cover where new construction connects to existing homes.
We can explore policy structures for eligible individual projects and ongoing building activity.
Eligible hinterland projects may be assessed depending on the site and proposed work. Sloping terrain, access, surrounding vegetation and construction methods may be relevant. The insurer determines acceptance and terms.
Not automatically. Some contract works policies distinguish between new construction and existing property. The insurer should be given accurate information about both so the available protection can be considered.
Builders should maintain suitable site drainage, storage and temporary weather protection. When reviewing insurance, check the treatment of storm, flood and other water-related damage. Insurers may apply specific terms depending on the site's risk profile.
Tell us about the project and Jenny Hoang will come back to you with questions or terms. Prefer to talk? Call 0468 034 450, Monday to Friday, 9:00am to 5:00pm.
Discuss Sunshine Coast construction insurance with PCIC Insurance on 0468 034 450.
No obligation to proceed. Monday to Friday, 9:00am to 5:00pm.
We also take enquiries from Caloundra, Maroochydore, Noosa, Nambour, the hinterland and Gympie.